In this Edition:
US POLITICS AND AI SCRUTINY REPRICE RISK
Democratic gains shifted the balance of power in Washington, while regulatory and investment concerns around AI fueled renewed volatility in the technology sector.
EUROPE BALANCES INFLATION AGAINST SLOWER GROWTH
European markets proved relatively resilient, but persistent inflation and softer activity left central banks balancing price stability against weakening economic momentum.
CHINA RALLIES AS JAPAN BEARS THE AI SELL-OFF
Chinese equities responded positively to fresh market-support measures, while Japan’s technology-heavy market suffered a sharp decline amid renewed AI concerns.
SOUTH AFRICAN ELECTIONS RESHAPE THE LOCAL OUTLOOK
Local assets strengthened as municipal election results signalled a major political shift, with attention now turning to coalition stability and service delivery.
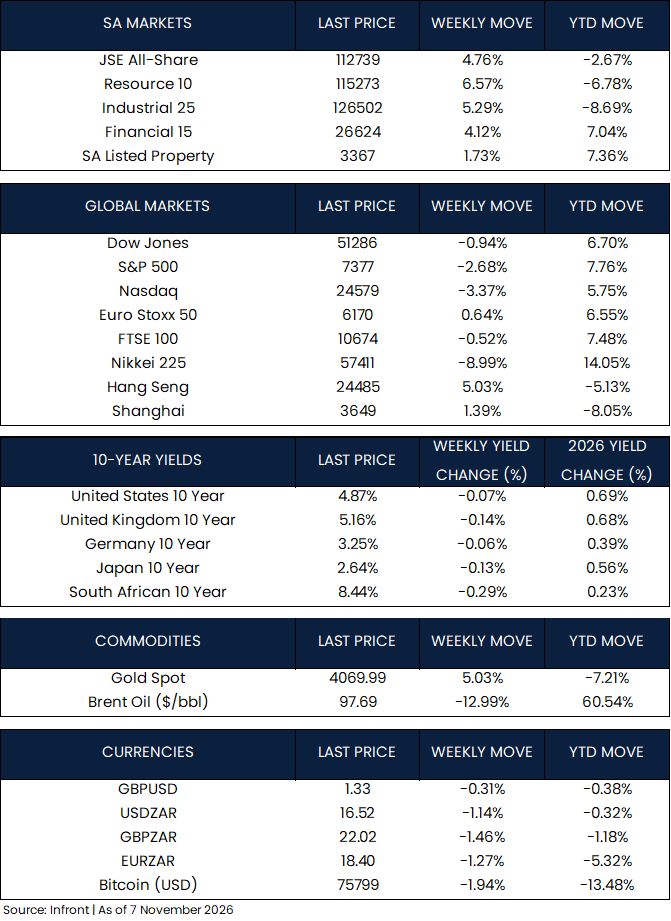
MARKET MOVES OF THE WEEK
Source: Infront as of 7 November
CHART OF THE WEEK
Source: State Street Investment Management, FactSet, S&P and MSCI. Data as of 5 November 2026.
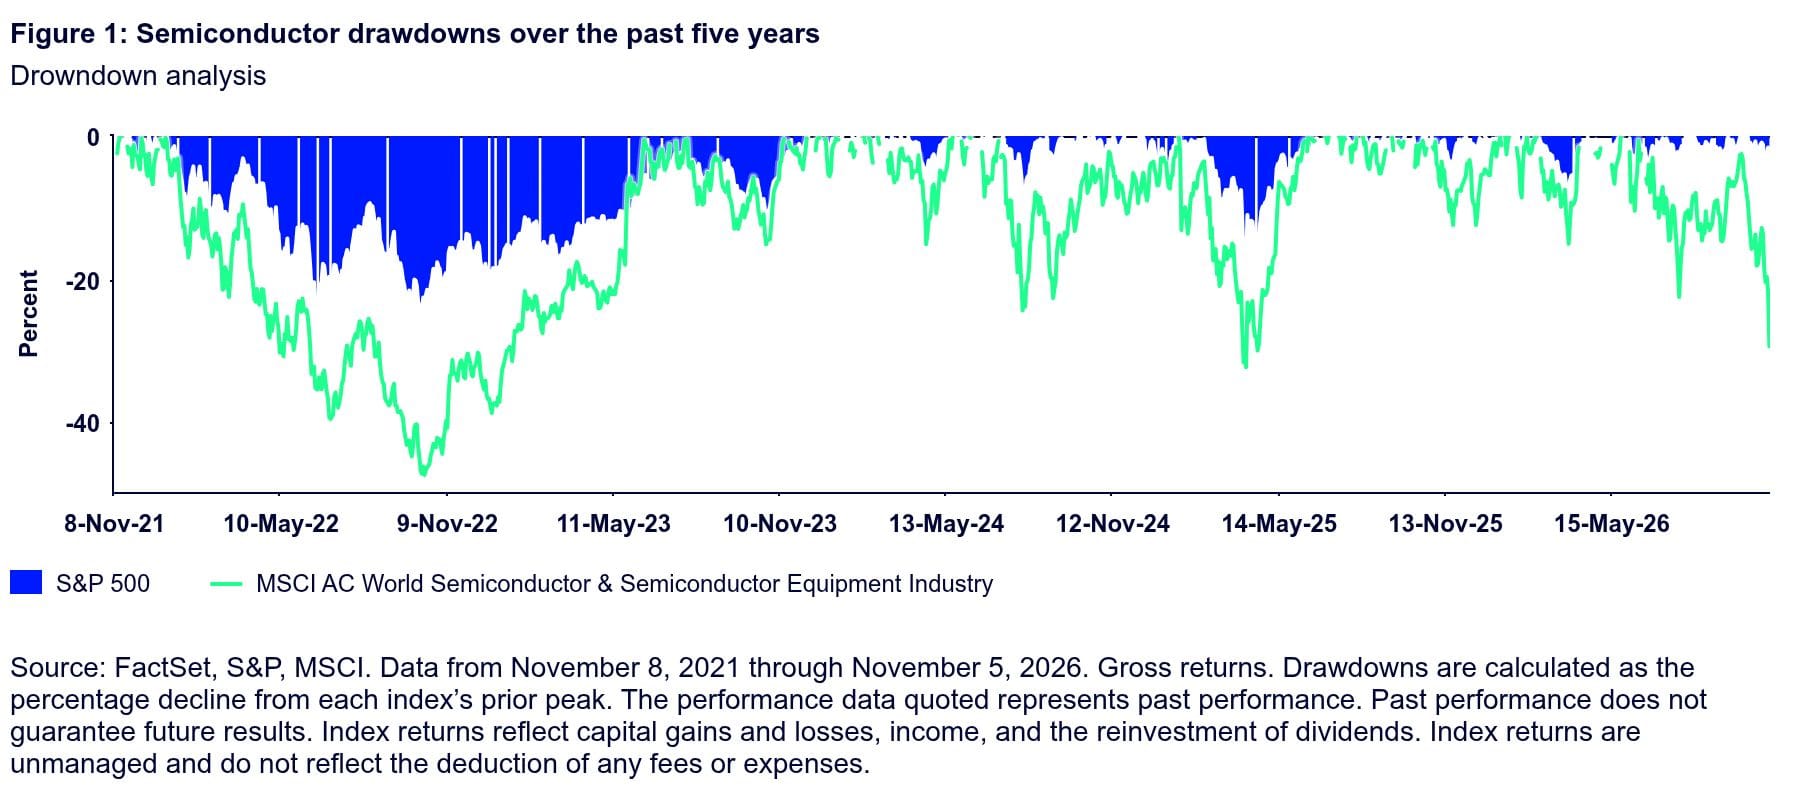
AI enthusiasm meets investor scrutiny
Semiconductor equities faced mounting headwinds prior to the US election, as heightened political ambiguity reinforced skepticism regarding the immense capital expenditure and ultimate return on investment within artificial intelligence. The accompanying chart contextualizes the recent retreat against historical downturns, underscoring the pronounced volatility inherent in concentrated technology exposures.
South African investors had an unusually strong local market week against a much more unsettled political backdrop. The JSE gained 4.76%, the rand strengthened to R16.52/$ and the 10-year government bond yield declined to 8.44%, while provisional municipal election results pointed to significant changes in the balance of local political power. The immediate market response is encouraging, but the longer-term investment significance will depend less on the election result itself than on whether coalition arrangements translate into improved infrastructure and service delivery. Offshore, renewed AI volatility and political change in Washington remain important for internationally diversified portfolios, while lower oil offers some welcome relief to the inflation outlook.
US Politics and AI Scrutiny Reprice Risk
US markets ended a volatile week lower as investors assessed the midterm election results, renewed concerns over artificial intelligence (AI) investment and stronger economic data. The S&P 500 declined 2.68%, while the technology-heavy Nasdaq lost 3.37% and the Dow Jones fell 0.94%. Democrats’ gains, which gave the party control of both chambers of Congress, initially supported hopes of easing geopolitical tensions. However, attention soon shifted to the possibility of tighter technology regulation and the implications for corporate earnings, contributing to a sharp sell-off before shares partially recovered on Friday.
The result changes the balance of power in Washington, giving Democrats greater influence over spending, legislation and scrutiny of the administration. For markets, a divided government could make large policy changes harder to deliver, while increasing the prospect of disputes over fiscal priorities. AI infrastructure emerged as a particular flashpoint, with concerns about electricity demand, water usage and the impact of data centres on local communities. Investors now face questions about both the commercial returns on AI spending and the political obstacles to delivering it.
Disappointing forecasts from major semiconductor companies added to concerns about whether substantial spending on AI infrastructure will deliver sufficient profits. Away from technology, economic conditions remained relatively firm. October’s employment report exceeded expectations, unemployment edged lower and manufacturing activity continued to expand. The Federal Reserve held interest rates steady at its latest meeting, with persistent inflation leaving further increases possible. US government bonds benefited from demand for safer assets, with the 10-year Treasury yield ending the last week at 4.87%.
Europe Balances Inflation Against Slower Growth
The Euro Stoxx 50 gained 0.64%, while the FTSE 100 declined 0.52%. Europe’s lower exposure to large technology companies provided some protection from the AI-related sell-off, while banking shares attracted interest. Brent crude fell 12.99% to $97.69 a barrel as hopes of renewed diplomacy with Iran reduced concerns about further disruption to energy supplies. The decline offered some relief to businesses and consumers facing elevated energy costs, although it weighed on energy producers.
Inflation nevertheless remained a challenge for policymakers. Eurozone inflation accelerated as earlier energy price increases continued to feed through, while business surveys and weaker retail sales pointed to slowing economic momentum. In the UK, the Bank of England raised interest rates and indicated that another increase could follow if price pressures persist. Services activity improved, but subdued retail footfall suggested households remained cautious. These contrasting signals leave central banks balancing the need to contain inflation against the risk of weakening growth.
China Rallies as Japan Bears the AI Sell-Off
China and Japan moved sharply in opposite directions. Hong Kong’s Hang Seng gained 5.03% and the Shanghai Composite rose 1.39%, supported by fresh measures from Beijing to encourage equity purchases and share buybacks. Investors returned to internet and technology shares following October’s weakness, although the global technology sell-off tempered the recovery towards the end of the last week. Economic surveys remained mixed, suggesting that policy support has helped market sentiment while a broader improvement in business conditions remains uneven.
Japan’s Nikkei 225 fell 8.99% as semiconductor and AI-related companies came under heavy selling pressure. Concerns about investment spending, valuations and potential US regulatory changes weighed on a market with significant exposure to the technology supply chain. Japanese government bonds benefited as investors sought safer assets. Stronger wage growth, however, continued to support the case for further Bank of Japan interest rate increases, complicating the policy outlook amid the market turbulence.
South African Elections Reshape the Local Outlook
South African markets enjoyed a strong week as investors assessed provisional municipal election results and developments abroad. The JSE All-Share gained 4.76%, led by resources, which rose 6.57%, while industrials advanced 5.29% and financials added 4.12%. Listed property gained 1.73%. Gold climbed 5.03%, providing a supportive backdrop for precious metals producers. The rand also strengthened, with the dollar falling 1.14% against the local currency to R16.52, while the South African 10-year government bond yield declined by 29 basis points to 8.44%.
Politically, the ANC faced a substantial setback, receiving around 31.8% of the national vote with more than 80% of ballots counted, almost 14 percentage points below its 2021 municipal election result. The DA led in Gauteng’s major metros, while MK challenged the ANC’s position in KwaZulu-Natal. With final results still outstanding, attention turned to coalition negotiations and the ability of incoming councils to address deteriorating infrastructure and service delivery.
Johannesburg illustrates the stakes: the city has experienced ten changes of mayor in a decade and faces a reported R220 billion infrastructure spending backlog. Early results put the DA ahead, but forming a workable majority could prove difficult given tensions between potential coalition partners. These elections determine municipal leadership rather than the national government, yet their economic relevance is substantial. Reliable water, electricity, roads and refuse collection directly affect businesses and households, making the durability of coalition agreements particularly important.
For investors, the longer-term significance will depend on whether these political shifts produce more stable municipal leadership and measurable improvements in local government. The election results signal a clear demand for change, but the next test will be whether parties can translate that mandate into functioning councils and better services.
The information contained in this recording/presentation is for general information purposes only and should not be construed as, nor does it constitute financial, tax, legal, investment or any other advice. Carrick does not guarantee the suitability or potential value of any products or investments discussed herein. We make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability or availability with respect to the information, products, services, or any other content contained in this recording for any purpose. Carrick accepts no responsibility for the suitability or accuracy of the information or for any errors or omissions that may occur. Therefore, any reliance you place on such information is strictly at your own risk. This material is provided for general information purposes only and is not personal advice to anyone to invest in any fund or product. Information taken from trade and other sources is believed to be reliable, although Carrick does not represent this as accurate or complete and it shouldn’t be relied upon as such. All material, content, and information provided by Carrick is the intellectual property of Carrick Group and its affiliates, unless otherwise stated. No part of this material may be copied, reproduced, distributed, published, or used for any commercial purpose without Carrick’s prior written consent, and is provided solely for non-commercial use. Capital is at risk. The value and income from investments can go down as well as up and are not guaranteed. An investor may get back significantly less than they invest. Past performance is not a reliable indicator of current or future performance and should not be the sole factor considered when selecting an investment.