In this Edition:
MARKET MOVES OF THE WEEK
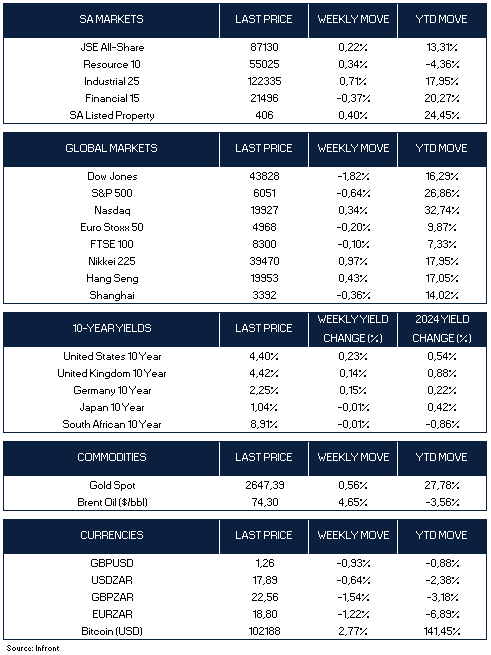
CHART OF THE WEEK
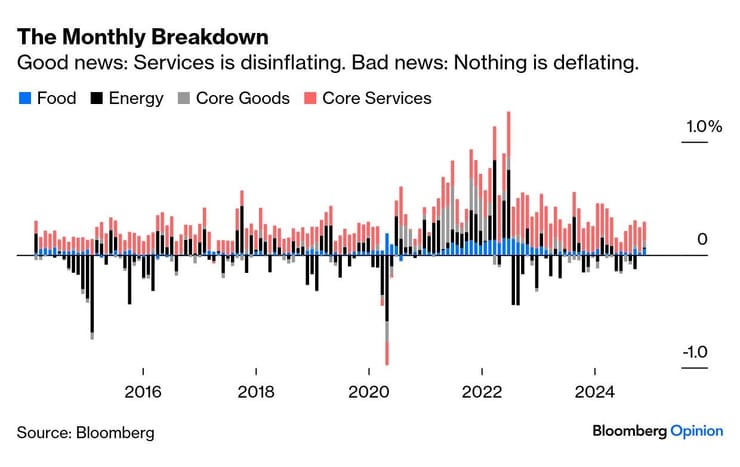
The latest U.S. inflation data for 2024 suggests the battle against rising prices is not yet definitively won. Headline inflation edged slightly higher to 2.7% from 2.6%, remaining within the Federal Reserve’s target range. However, a closer look reveals that persistent price increases in services, particularly core services, continue to pose challenges. Resolving this inflation uncertainty in the coming months could have significant implications for the global economy and may even necessitate adjustments to proposed Trump 2.0 tax and trade policies. Source: Bloomberg
The Nasdaq briefly surpassed the 20,000 mark this week, reflecting a year of robust U.S. economic growth, rising corporate profits, moderating inflation, and central-bank easing. However, as inflation progress slowed in the fourth quarter, questions arise about the Federal Reserve’s future policy direction.
U.S. consumer inflation data for November showed prices rising by 0.3% month-on-month, with core annual inflation holding steady at 3.3% for the third month in a row. While inflation has eased considerably from its peak of 6.6% in 2022, it remains above the Federal Reserve’s 2% target. November’s CPI data is the last major input before the Fed’s meeting on 17-18 December. The market expects the Fed to deliver a 25 basis point cut at its December meeting, but may slow the pace of rate cuts in 2025 amid persistent inflation uncertainties.
Meanwhile, U.S. employment data showed signs of a softening labour market as initial jobless claims reached a two-month high of 242,000, and continuing claims hovered near three-year highs. This trend suggests longer job search durations, aligning with gradual labour market adjustments.
The European Central Bank (ECB) cut its deposit rate by 25 basis points to 3.0% but signalled a cautious stance on future easing, while the Swiss National Bank (SNB) surprised with a larger cut of 50 basis points to 0.5% amid easing inflationary pressures. Meanwhile, UK GDP unexpectedly contracted by 0.1% in October on weak industrial production and manufacturing.
In Japan, speculation grew that the Bank of Japan (BoJ) may delay an interest rate hike at its December 18–19 meeting, weakening the yen to the mid-JPY 153 range against the USD. While expectations for a rate hike were initially split between December and January, consensus now favours a January hike. This delay allows the BoJ to consider additional inflation data, its quarterly economic report, and regional feedback. Meanwhile, Japan’s economy exceeded expectations in Q3, with GDP growing 0.3% quarter-on-quarter.
China announced plans for increased fiscal spending and public borrowing in 2025 to bolster domestic consumption. However, economic data highlighted ongoing deflationary pressures, with consumer prices rising just 0.2% year-on-year in November. Export growth slowed while imports declined further, underscoring the economy’s challenges.
Global markets delivered mixed results this week. In the U.S., the Dow Jones declined 1.82%, the S&P 500 slipped 0.64%, while the Nasdaq gained 0.34%. European markets edged lower, with the Euro Stoxx 50 down 0.20% and the FTSE 100 losing 0.10%. In Asia, Japan’s Nikkei 225 rose 0.97%, and Hong Kong’s Hang Seng advanced 0.43%, while the Shanghai Composite dipped 0.36%. Brent Crude surged 4.65%, closing at $74.30 per barrel, while developed market bond yields rose.
South Africa’s SACCI Business Confidence Index rose to 118.1 in November, marking the largest year-on-year improvement since late 2022. Confidence was driven by higher tourist arrivals, stronger precious metal prices, increased vehicle sales, and optimism surrounding the coalition government formed after June’s election.
However, challenges persist in the labour market. Stats SA reported that the formal non-agricultural sector shed 133,000 jobs in the third quarter, reducing employment to 10.62 million from 10.74 million in June. Meanwhile, consumer inflation rose to 2.9% year-on-year in November, slightly below expectations.
The JSE All Share Index gained 0.22% over the week, supported by industrial (+0.70%) and resource (+0.34%) sectors, while the financial sector declined 0.37%. The rand strengthened to R17.89 against the U.S. Dollar, and the SA 10-Year Bond Yield held steady at 8.91%.
The information contained in this recording/presentation is for general information purposes only and should not be construed as, nor does it constitute financial, tax, legal, investment or any other advice. Carrick does not guarantee the suitability or potential value of any products or investments discussed herein. We make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability or availability with respect to the information, products, services, or any other content contained in this recording for any purpose. Carrick accepts no responsibility for the suitability or accuracy of the information or for any errors or omissions that may occur. Therefore, any reliance you place on such information is strictly at your own risk. This material is provided for general information purposes only and is not personal advice to anyone to invest in any fund or product. Information taken from trade and other sources is believed to be reliable, although Carrick does not represent this as accurate or complete and it shouldn’t be relied upon as such. All material, content, and information provided by Carrick is the intellectual property of Carrick Group and its affiliates, unless otherwise stated. No part of this material may be copied, reproduced, distributed, published, or used for any commercial purpose without Carrick’s prior written consent, and is provided solely for non-commercial use. Capital is at risk. The value and income from investments can go down as well as up and are not guaranteed. An investor may get back significantly less than they invest. Past performance is not a reliable indicator of current or future performance and should not be the sole factor considered when selecting an investment.